Meiji Japan and post-Soviet Russia · CHAPTER 11 ·
Oligarchs and the First Chechen War
Chapter 11 of Remaking the State: Meiji Japan 1600–1912 and Post-Soviet Russia 1964–2000: “A State at War with Itself”
Russia in the mid-1990s was a state too weak to collect taxes, pay soldiers and teachers, or govern its regions. Tatarstan signed a treaty with Moscow in February 1994, Chechnya was invaded in December 1994, and the loans-for-shares auctions of late 1995 made the oligarchs a power in politics.
Chapter 11 is part of membership. WW2 is free — every chapter. Try chapters 1–2 of any 2 other atlases (3 with a free account). Opening a new atlas uses one of them. Membership opens all 21 — Join.
Free printable Meiji Japan and post-Soviet Russia study guide, sent by email ↓
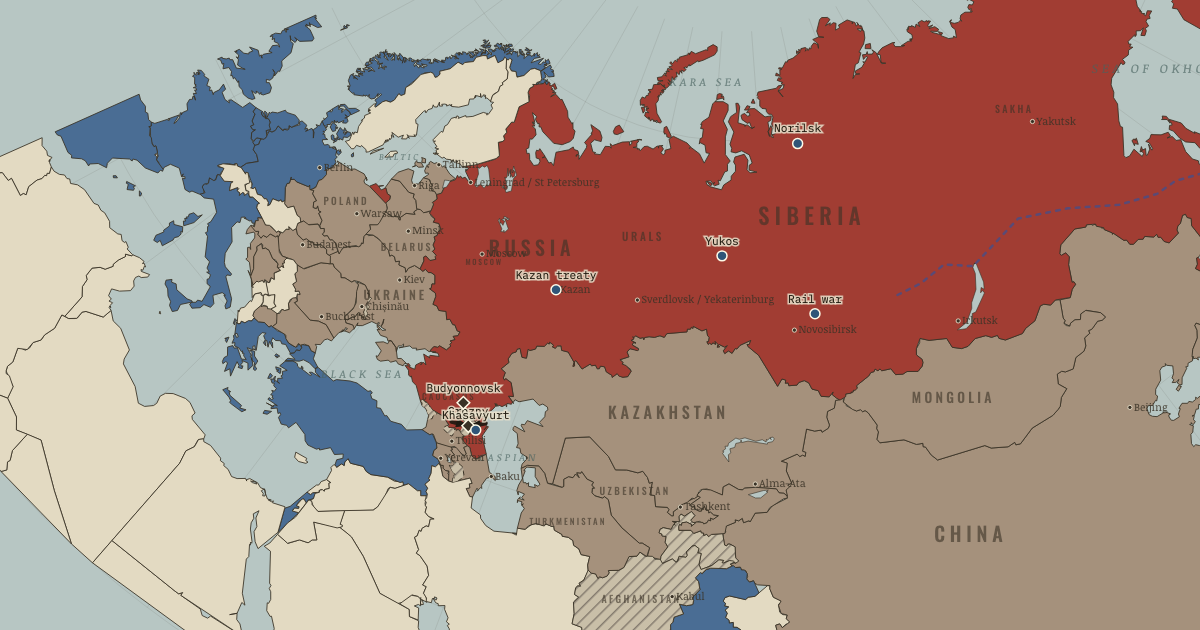
The map above is the world of Russia and the former Soviet Union, August 1996 — Khasavyurt; Yeltsin re-elected.
Part of IB History: Meiji Japan and post-Soviet Russia →
BRIEF EXPLANATION — THE ESSENTIAL ARGUMENT
The disasters of Russia’s middle 1990s had a common root: a state too weak to collect its taxes, pay its soldiers and teachers, or govern its own regions. Two republics inside Russia, homelands of non-Russian peoples with their own constitutions, show the choices that weak state faced. Tatarstan, which had declared itself sovereign in 1990, claiming that its own laws came first, much as a state might claim priority over federal law, signed a treaty with Moscow in February 1994 and stayed inside the federation on generous terms, so its dashed outline disappears from the map after 1994. Chechnya, which had declared full independence in 1991, was invaded in December 1994. Three Russian columns, the arrows on the map, converged on Grozny, and the city was taken by bombardment that killed tens of thousands of civilians, many of them elderly ethnic Russians with nowhere to go. The war ended only after Chechen fighters retook Grozny in August 1996 and Moscow signed the accord of Khasavyurt.
In the same years the state sold its most valuable companies to pay its bills. Under the loans-for-shares scheme of 1995, a few bankers lent the government money in exchange for the right to manage state shares in firms such as Norilsk Nickel and Yukos; when the state failed to repay, as everyone expected, the banks kept the companies. These men, soon called oligarchs, meaning tycoons who use wealth to gain political power, financed and televised Yeltsin’s comeback in the 1996 election, which he won after his approval had fallen to single digits. Tax revenue kept falling, wages and pensions went unpaid, and miners blocked the Trans-Siberian Railway in the rail war of May 1998. In August 1998 the government defaulted, failing to pay its debts like a bankrupt borrower, and the rouble collapsed. The decade’s disasters came from a state that could neither tax its new rich nor control its own army.
The full story
Russia’s weakness began with the bargain that held the federation together. During the struggle with Gorbachev, Yeltsin had told the republics inside Russia, homelands of non-Russian peoples, to “take as much sovereignty as you can swallow”, and Tatarstan, Sakha and others declared themselves sovereign in 1990, claiming that their laws overrode Moscow’s, the dashed outlines on the maps of 1990–94. Regional leaders kept tax revenue, controlled local police and courts and struck deals with Moscow. Tatarstan, an oil-rich Volga republic whose population was about two-fifths Russian, held a referendum on sovereignty in 1992 and then signed a treaty in February 1994 that left it inside Russia with control over its oil, budget and much of its law. Dozens of regions signed similar deals by 1998. Federal tax collection collapsed, firms paid each other in goods, and the state paid teachers, doctors and soldiers months late. Russia held together by bargaining, and the bargains left the centre short of money and authority.
Chechnya shows what happened when bargaining failed and a weak state chose force. Dzhokhar Dudayev, a former Soviet air force general, had declared Chechnya independent in November 1991, and Russian troops withdrew in 1992. In December 1994, after a covert attempt to oust him had failed, Yeltsin ordered an invasion. Three columns advanced on Grozny from the north, west and east, and the New Year’s Eve assault ended in disaster for poorly trained conscripts, young men drafted for compulsory service. The army then took the city by artillery and air bombardment that killed tens of thousands of civilians by March 1995. In June 1995 fighters under Shamil Basayev seized a hospital in the southern Russian town of Budyonnovsk, taking more than 1,500 hostages; about 130 people died by the official count and about 165 by others. In August 1996 Chechen fighters retook Grozny, and Alexander Lebed signed the Khasavyurt accord, which ended the war and postponed the question of independence. Estimates of the dead run from about 35,000 to 100,000, most of them civilians.
The state that could not win in Chechnya also sold its best assets to the men who financed it. In 1995 the banker Vladimir Potanin proposed that banks lend the government money secured on its shares in major companies, and the very banks that bid then ran the auctions. Potanin’s Oneximbank took Norilsk Nickel for $170.1 million, and Mikhail Khodorkovsky’s Menatep took Yukos for about $309 million. These oligarchs, tycoons with political power, and their television channels then backed Yeltsin against the Communist Gennady Zyuganov in 1996, and he won the run-off with 53.8%. Yet the state still could not tax the economy. It borrowed through short-term bonds, IOUs repayable within months, at ever higher interest rates, wages went unpaid, and in May 1998 miners blocked railways in the rail war. When oil prices fell and investors fled after the Asian financial crisis, the government defaulted on 17 August 1998 and the rouble lost about two-thirds of its value within weeks. Privatised wealth and public poverty had grown side by side, and in 1998 the bill for both arrived together.
DEEP EXPLANATION — EVIDENCE & INTERPRETATION
Why war in Chechnya and a treaty in Tatarstan?
Both republics declared sovereignty in 1990, and scholars comparing them, including Anatol Lieven, Carlotta Gall and Thomas de Waal, point to differences of geography, history and leadership. Tatarstan lies deep inside Russia, surrounded by Russian regions, with a large Russian population and an economy tied to Russian markets; its president, Mintimer Shaimiev, was a former Soviet party chief who wanted a better deal inside Russia. Chechnya lies on Russia’s southern border, and its people carried the memory of 1944, when Stalin deported the entire Chechen nation to Central Asia and a large share died in transit and exile. Dudayev demanded full independence, while criminal networks and smuggling flourished in the unrecognised state. Moscow’s own choices mattered as well. The defence minister Pavel Grachev claimed Grozny could be taken quickly with a single airborne regiment, and Yeltsin’s advisers expected a short, popular war. Geography and history made Chechnya harder, and decisions in Moscow turned difficulty into catastrophe.
Loans-for-shares and the birth of the oligarchs
Chrystia Freeland’s Sale of the Century and David Hoffman’s The Oligarchs describe loans-for-shares as the moment when Russia’s richest bankers turned themselves into owners of its natural resources. The scheme was presented as a way to raise money for a desperate budget, but the auctions were organised by the same banks that won them, rival bids were disqualified on technicalities, and the prices paid were a small fraction of what the companies were later worth. Its political purpose was as important as its financial one. Facing defeat in 1996, Yeltsin needed the support of the men whose banks and television channels could run his campaign, and the auctions bound their fortunes to his survival. Daniel Treisman has argued that the economic damage has been exaggerated, since several of the firms were run more efficiently afterwards. The damage to legitimacy was lasting: most Russians came to see private property as the product of insider deals, which later made it easier for the state to take it back.
The 1998 default: a state that could not tax
The default of August 1998 was a fiscal crisis at its core. Federal revenue had shrunk because large firms paid taxes late, in goods or not at all, and because regions kept much of what they collected. The government covered its deficits by selling short-term bonds, known as GKOs, at interest rates that rose above 50% a year, which attracted foreign investors and created a debt the state could repay only by borrowing more. When the Asian financial crisis of 1997 frightened investors and the oil price fell towards ten dollars a barrel, the scheme collapsed despite an IMF-led rescue package in July 1998. On 17 August the government defaulted on its domestic bonds, froze some foreign payments and let the rouble float; it fell from about six to the dollar to more than twenty within weeks. Banks failed and savings were lost for the second time in a decade. Yet the cheaper rouble made Russian goods competitive, and output grew by 6.4% in 1999.
Key places on the map
On this day
Why it happened
The state could not collect its own taxes. Privatisation and inflation had left a state whose revenue depended on large firms that paid late, in goods or not at all. The regions kept much of what they collected, and the new rich moved money abroad. Without revenue the government could not pay its army, its officials or its debts, and every crisis of these years, from the poor performance of conscripts in Grozny to the default of 1998, grew from that gap.
The regions had taken power as the Union fell. In 1990–91 Yeltsin had encouraged the republics inside Russia to claim sovereignty in order to weaken Gorbachev. Afterwards Moscow had to negotiate with regional leaders who controlled resources, police and votes. Bilateral treaties kept most of them inside the federation, and they also turned Russia into a patchwork of special deals, an echo of the domains that Japan’s leaders had abolished in 1871.
Chechnya’s history made compromise harder. The Chechens had resisted Russian conquest in the nineteenth century and suffered the deportation of their entire nation in 1944, from which survivors returned only in 1957. Dudayev’s demand for full independence drew on that memory, and the absence of Russian authority after 1991 allowed weapons and smuggling to flourish. Moscow’s refusal to negotiate seriously with an elected Chechen leader and its belief in a quick victory turned a political problem into a war.
The government needed cash and a re-election. Yeltsin’s government turned to the banks because it needed cash and a re-election at once, with the budget empty and the 1996 election approaching. Under the loans-for-shares scheme, banks lent the treasury money against shares in the best state companies, and when the state did not repay they auctioned the shares, usually to themselves, much like a pawnbroker selling an unredeemed pledge to his own relatives. Once they owned the companies, the bankers had every reason to keep Yeltsin in power. Short-term political survival thus shaped one of the largest transfers of wealth in modern history.
THE TURNING POINT
Loans-for-shares, November–December 1995. The auctions of late 1995 are the hinge of this chapter because they fused wealth and power in a way that defined Russian capitalism. A handful of bankers acquired oil, nickel and other natural resources for a fraction of their value, because the banks that organised the auctions also bid in them and kept rivals out, and in return they financed and broadcast Yeltsin’s re-election campaign. The deal saved Yeltsin in 1996 and discredited privatisation for a generation. It also showed that the Russian state, too weak to tax these companies, was strong enough to give them away.
What it changed
Oligarchs became a power in politics. After 1996 men such as Boris Berezovsky and Vladimir Gusinsky used their banks and television channels to influence ministers and elections, and Berezovsky briefly served as deputy head of the Security Council. Their power depended on the Kremlin’s weakness. When a stronger president arrived, he would move against the most political of them first.
An unresolved war and a humiliated army. The Khasavyurt accord left Chechnya effectively independent, ruled by the elected president Aslan Maskhadov, who struggled to control warlords and kidnapping gangs. Many officers regarded the accord as a betrayal, and many Russians blamed Chechens for kidnappings and bombings. Raids from Chechnya into neighbouring Dagestan in 1999 would provide the occasion for a second war.
The default cleared the ground for recovery. The devaluation of 1998 made imported goods expensive and Russian products competitive, and output began to grow in 1999. When oil prices rose again, the state’s revenue recovered quickly. Yeltsin’s successor would govern a country emerging from its deepest crisis, with a budget refilled by oil, and he would take much of the credit for the recovery.
DISCUSSION QUESTION — Were Russia’s oligarchs a product of weak state institutions, or the cause of their weakness?
The case that weak institutions produced the oligarchs is strong: courts could not enforce contracts, the tax service could not collect revenue, and a government desperate for money and votes traded assets for loans and support, so the oligarchs were filling a vacuum. The case that they deepened the weakness is also strong. Once they owned media, banks and natural resources, they lobbied for tax exemptions, captured regulators and used their channels to shape elections, which kept the state weak. Writers such as the journalist David Hoffman and the political scientist Daniel Treisman describe a cycle in which each fed the other. A strong answer explains the mechanism of that cycle with evidence, such as loans-for-shares and the 1996 election, and asks why it was broken only by a president who restored central power by curbing the media and the courts as well. The transferable insight is that markets built before the rule of law tend to create owners who prefer to keep the law weak.
An interesting fact
Boris Yeltsin’s 1996 campaign used the slogan “Vote or lose”, aimed at young voters, and in June the 65-year-old president danced on stage at a rock concert in Rostov-on-Don in front of the cameras. Just over two weeks later, between the two rounds of voting, he suffered a serious heart attack. His staff kept it secret, showing old footage and issuing statements in his name, and voters learned the truth only after he had won the run-off. In November he underwent quintuple bypass surgery, performed by the Russian surgeon Renat Akchurin with the American heart surgeon Michael DeBakey advising.
Related
THE FREE PRINTABLE STUDY GUIDE
Join the Dispatch — a short welcome series, then a letter when a new atlas opens — and the printable study guide for Remaking the State is yours now, free.
NO TRACKING · YOUR ADDRESS IS USED FOR THE DISPATCH AND NOTHING ELSE · UNSUBSCRIBE ANYTIME