Meiji Japan and post-Soviet Russia · 1996
Did Russia’s oligarchs cause or exploit a weak state?
The seminar question: “Were Russia’s oligarchs a product of weak state institutions, or the cause of their weakness?”
Russia in the mid-1990s was a state too weak to collect taxes, pay soldiers and teachers, or govern its regions. Tatarstan signed a treaty with Moscow in February 1994, Chechnya was invaded in December 1994, and the loans-for-shares auctions of late 1995 made the oligarchs a power in politics.
Chapter 11 is part of membership. WW2 is free — every chapter. Try chapters 1–2 of any 2 other atlases (3 with a free account). Opening a new atlas uses one of them. Membership opens all 21 — Join.
Free printable Meiji Japan and post-Soviet Russia study guide, sent by email ↓
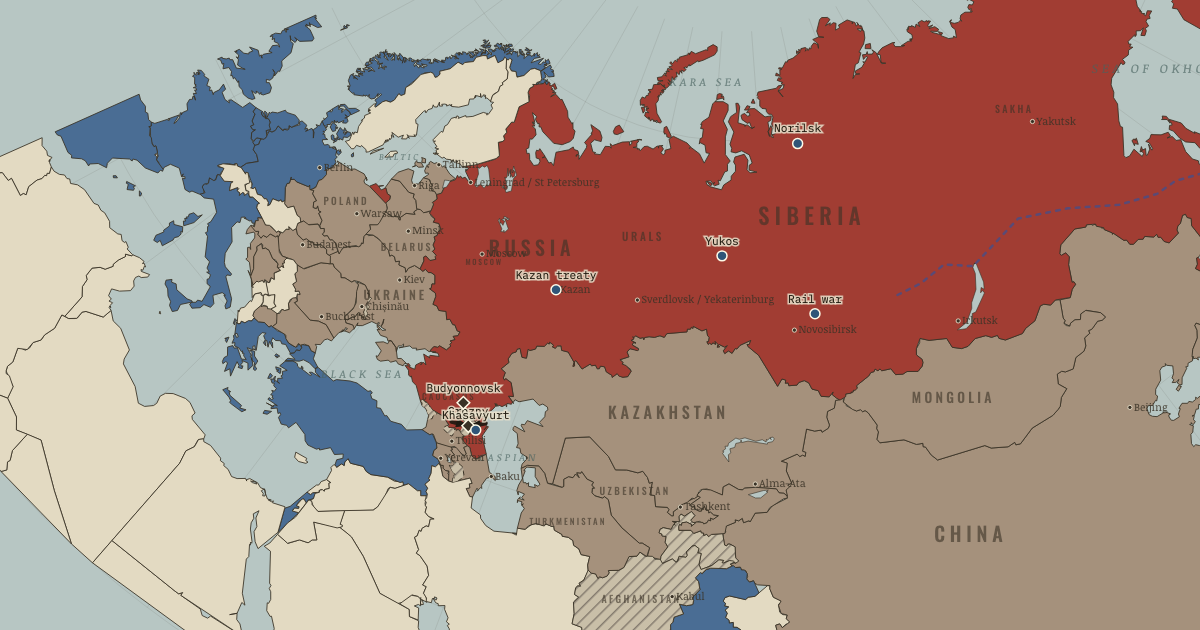
Russia’s weakness began with the bargain that held the federation together. During the struggle with Gorbachev, Yeltsin had told the republics inside Russia, homelands of non-Russian peoples, to “take as much sovereignty as you can swallow”, and Tatarstan, Sakha and others declared themselves sovereign in 1990, claiming that their laws overrode Moscow’s, the dashed outlines on the maps of 1990–94. Regional leaders kept tax revenue, controlled local police and courts and struck deals with Moscow. Tatarstan, an oil-rich Volga republic whose population was about two-fifths Russian, held a referendum on sovereignty in 1992 and then signed a treaty in February 1994 that left it inside Russia with control over its oil, budget and much of its law. Dozens of regions signed similar deals by 1998. Federal tax collection collapsed, firms paid each other in goods, and the state paid teachers, doctors and soldiers months late. Russia held together by bargaining, and the bargains left the centre short of money and authority.
The short answer
- The state could not collect its own taxes. Privatisation and inflation had left a state whose revenue depended on large firms that paid late, in goods or not at all. The regions kept much of what they collected, and the new rich moved money abroad. Without revenue the government could not pay its army, its officials or its debts, and every crisis of these years, from the poor performance of conscripts in Grozny to the default of 1998, grew from that gap.
- The regions had taken power as the Union fell. In 1990–91 Yeltsin had encouraged the republics inside Russia to claim sovereignty in order to weaken Gorbachev. Afterwards Moscow had to negotiate with regional leaders who controlled resources, police and votes. Bilateral treaties kept most of them inside the federation, and they also turned Russia into a patchwork of special deals, an echo of the domains that Japan’s leaders had abolished in 1871.
- Chechnya’s history made compromise harder. The Chechens had resisted Russian conquest in the nineteenth century and suffered the deportation of their entire nation in 1944, from which survivors returned only in 1957. Dudayev’s demand for full independence drew on that memory, and the absence of Russian authority after 1991 allowed weapons and smuggling to flourish. Moscow’s refusal to negotiate seriously with an elected Chechen leader and its belief in a quick victory turned a political problem into a war.
- The government needed cash and a re-election. Yeltsin’s government turned to the banks because it needed cash and a re-election at once, with the budget empty and the 1996 election approaching. Under the loans-for-shares scheme, banks lent the treasury money against shares in the best state companies, and when the state did not repay they auctioned the shares, usually to themselves, much like a pawnbroker selling an unredeemed pledge to his own relatives. Once they owned the companies, the bankers had every reason to keep Yeltsin in power. Short-term political survival thus shaped one of the largest transfers of wealth in modern history.
THE TURNING POINT
Loans-for-shares, November–December 1995. The auctions of late 1995 are the hinge of this chapter because they fused wealth and power in a way that defined Russian capitalism. A handful of bankers acquired oil, nickel and other natural resources for a fraction of their value, because the banks that organised the auctions also bid in them and kept rivals out, and in return they financed and broadcast Yeltsin’s re-election campaign. The deal saved Yeltsin in 1996 and discredited privatisation for a generation. It also showed that the Russian state, too weak to tax these companies, was strong enough to give them away.
What it changed
Oligarchs became a power in politics. After 1996 men such as Boris Berezovsky and Vladimir Gusinsky used their banks and television channels to influence ministers and elections, and Berezovsky briefly served as deputy head of the Security Council. Their power depended on the Kremlin’s weakness. When a stronger president arrived, he would move against the most political of them first.
An unresolved war and a humiliated army. The Khasavyurt accord left Chechnya effectively independent, ruled by the elected president Aslan Maskhadov, who struggled to control warlords and kidnapping gangs. Many officers regarded the accord as a betrayal, and many Russians blamed Chechens for kidnappings and bombings. Raids from Chechnya into neighbouring Dagestan in 1999 would provide the occasion for a second war.
The default cleared the ground for recovery. The devaluation of 1998 made imported goods expensive and Russian products competitive, and output began to grow in 1999. When oil prices rose again, the state’s revenue recovered quickly. Yeltsin’s successor would govern a country emerging from its deepest crisis, with a budget refilled by oil, and he would take much of the credit for the recovery.
The full answer, argued
The case that weak institutions produced the oligarchs is strong: courts could not enforce contracts, the tax service could not collect revenue, and a government desperate for money and votes traded assets for loans and support, so the oligarchs were filling a vacuum. The case that they deepened the weakness is also strong. Once they owned media, banks and natural resources, they lobbied for tax exemptions, captured regulators and used their channels to shape elections, which kept the state weak. Writers such as the journalist David Hoffman and the political scientist Daniel Treisman describe a cycle in which each fed the other. A strong answer explains the mechanism of that cycle with evidence, such as loans-for-shares and the 1996 election, and asks why it was broken only by a president who restored central power by curbing the media and the courts as well. The transferable insight is that markets built before the rule of law tend to create owners who prefer to keep the law weak.
An interesting fact
Boris Yeltsin’s 1996 campaign used the slogan “Vote or lose”, aimed at young voters, and in June the 65-year-old president danced on stage at a rock concert in Rostov-on-Don in front of the cameras. Just over two weeks later, between the two rounds of voting, he suffered a serious heart attack. His staff kept it secret, showing old footage and issuing statements in his name, and voters learned the truth only after he had won the run-off. In November he underwent quintuple bypass surgery, performed by the Russian surgeon Renat Akchurin with the American heart surgeon Michael DeBakey advising.
This is the study layer of Oligarchs and the First Chechen War, chapter 11 of Remaking the State: Meiji Japan 1600–1912 and Post-Soviet Russia 1964–2000; the full index of the atlas is here.
Related questions
THE FREE PRINTABLE STUDY GUIDE
Join the Dispatch — a short welcome series, then a letter when a new atlas opens — and the printable study guide for Remaking the State is yours now, free.
NO TRACKING · YOUR ADDRESS IS USED FOR THE DISPATCH AND NOTHING ELSE · UNSUBSCRIBE ANYTIME